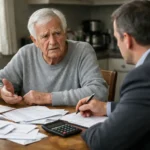

At 81, he sold his $75,000 house to pay off his daughter’s $50,000 debt and now has no money set aside for his own needs. The transaction has left the elder financially exposed and raises immediate questions about housing, access to care and eligibility for public benefits. Family members, advisors and professionals now face the task of determining whether the sale was voluntary, whether proper legal safeguards were observed and what options remain for covering the elder’s living and health costs.
Such a transfer can have concrete administrative implications. The sale proceeds, if retained or spent in certain ways, may affect qualification for means-tested programs with asset limits and look-back rules. For information on federal programs and state-administered rules, consult Medicaid and the relevant state agency; a starting point is Medicaid. Because rules vary by state and by program, an assessment by a qualified elder law attorney or a benefits counselor is often necessary to map available supports.
There is also a legal and protective dimension. When an older adult parts with a major asset and ends up without provisions for basic needs, authorities and advocates may examine whether undue influence or financial exploitation occurred. Local Adult Protective Services and long-term care ombudsmen handle reports of potential abuse and can investigate if coercion or deception is suspected. For federal aging services information, resources are available via the Administration for Community Living. Consulting specialists in elder law can clarify options around guardianship, powers of attorney and potential remedies.
Practically, immediate steps include documenting the transaction, compiling bank and title records, and contacting local aging services to explore community-based supports and housing options. Families should consider emergency housing alternatives and benefits screening while seeking pro bono or low-cost legal advice. For guidance on care planning and service options, look into resources on elder care and long-term care to understand possible pathways for stabilizing the elder’s situation without creating further financial hardship.