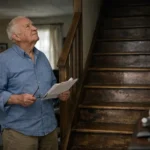
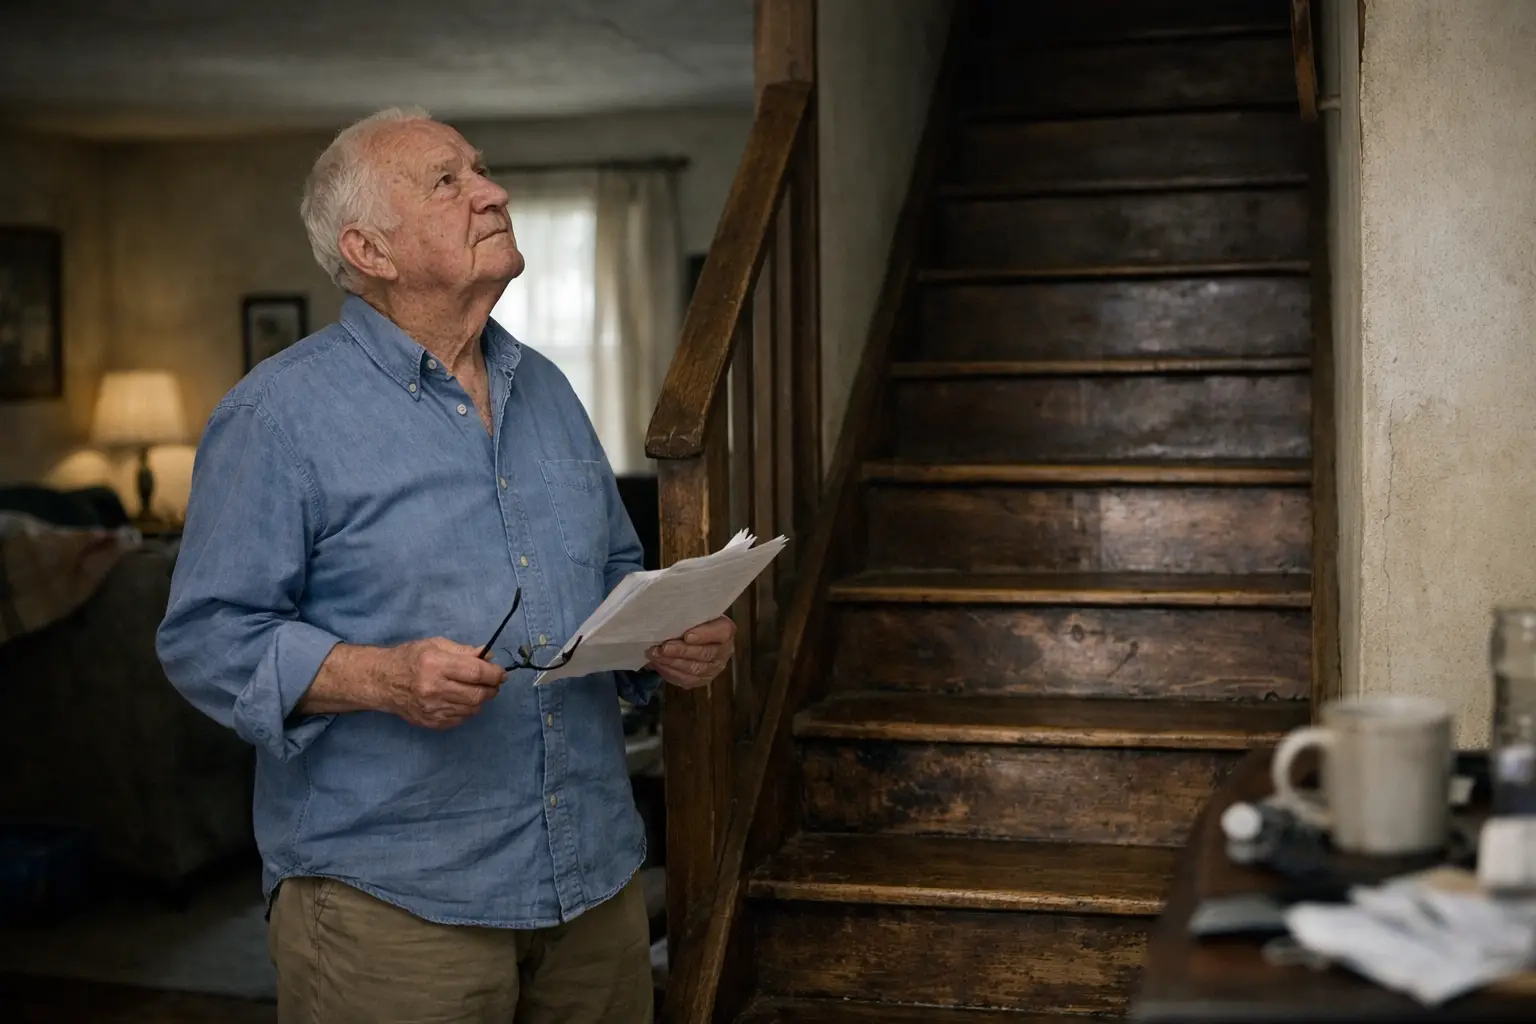
An 80-year-old homeowner faces a difficult choice: keep a home with about $400,000 in equity and a low-interest mortgage, or sell because the stairs have become hazardous. The question surfaces common themes for older homeowners: the tension between preserving a favorable mortgage rate and addressing safety and mobility needs. For those considering staying, aging in place adaptations range from modest modifications to more extensive renovations that can alter daily life but may carry significant upfront cost.
The alternatives typically include renovating to improve safety, selling and downsizing, or using home-based financing to pay for work. Renovations might involve installing stair lifts, reconfiguring living spaces, or creating single-floor living, while selling can free up capital and remove maintenance responsibilities. Borrowing against property value is an option, but homeowners should understand how loan terms interact with an existing mortgage and long-term finances. For information on reverse mortgages and consumer safeguards, consult Consumer Financial Protection Bureau.
Decisions hinge on more than immediate cost. Safety considerations, future care needs, local housing market conditions and the homeowner’s social support all matter. Professional assessments can clarify the scope of necessary work and realistic budgets: an occupational therapist can recommend mobility solutions, while contractors can provide cost estimates and timelines. Financial advisors can model outcomes for staying versus selling, including implications for heirs and ongoing expenses. Resources on senior housing and services may be useful; organizations such as AARP offer practical guides on home modifications and long-term planning.
Practical next steps include obtaining multiple contractor quotes, securing a safety assessment, and checking mortgage terms with the lender before pursuing financing. Weigh short-term fixes against long-term needs and the potential benefits of downsizing or relocating. Whatever path is chosen, prioritizing immediate safety while mapping financial consequences will help translate an urgent home hazard into a sustainable housing plan. For ongoing topics on housing and retirement, see real estate and retirement resources.