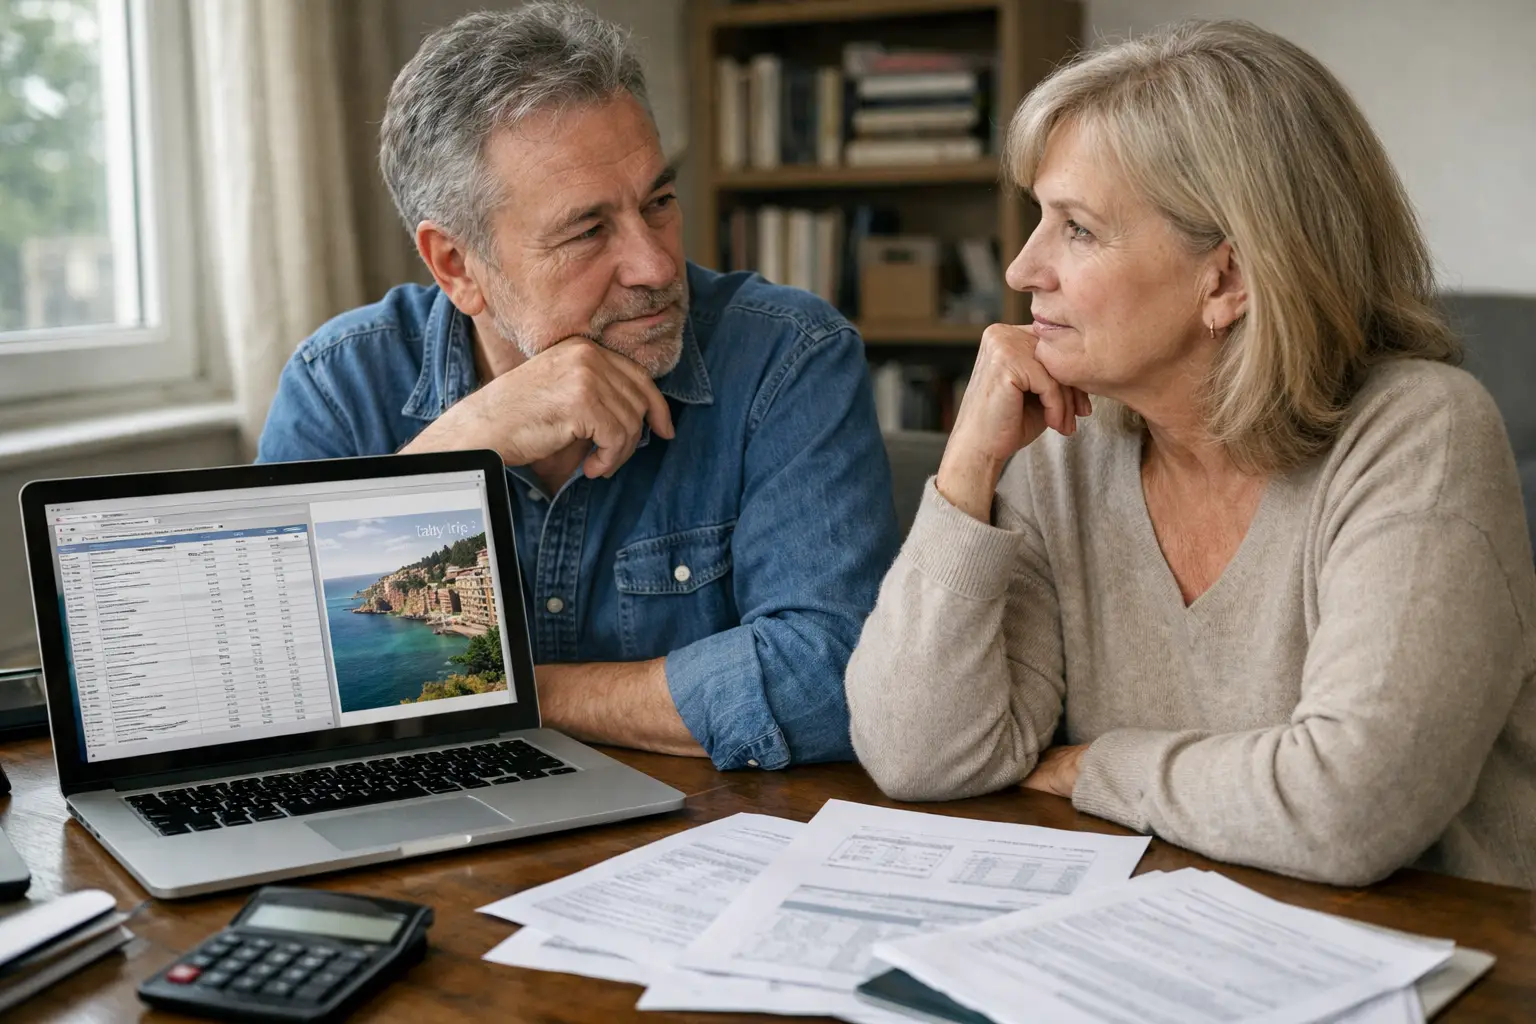
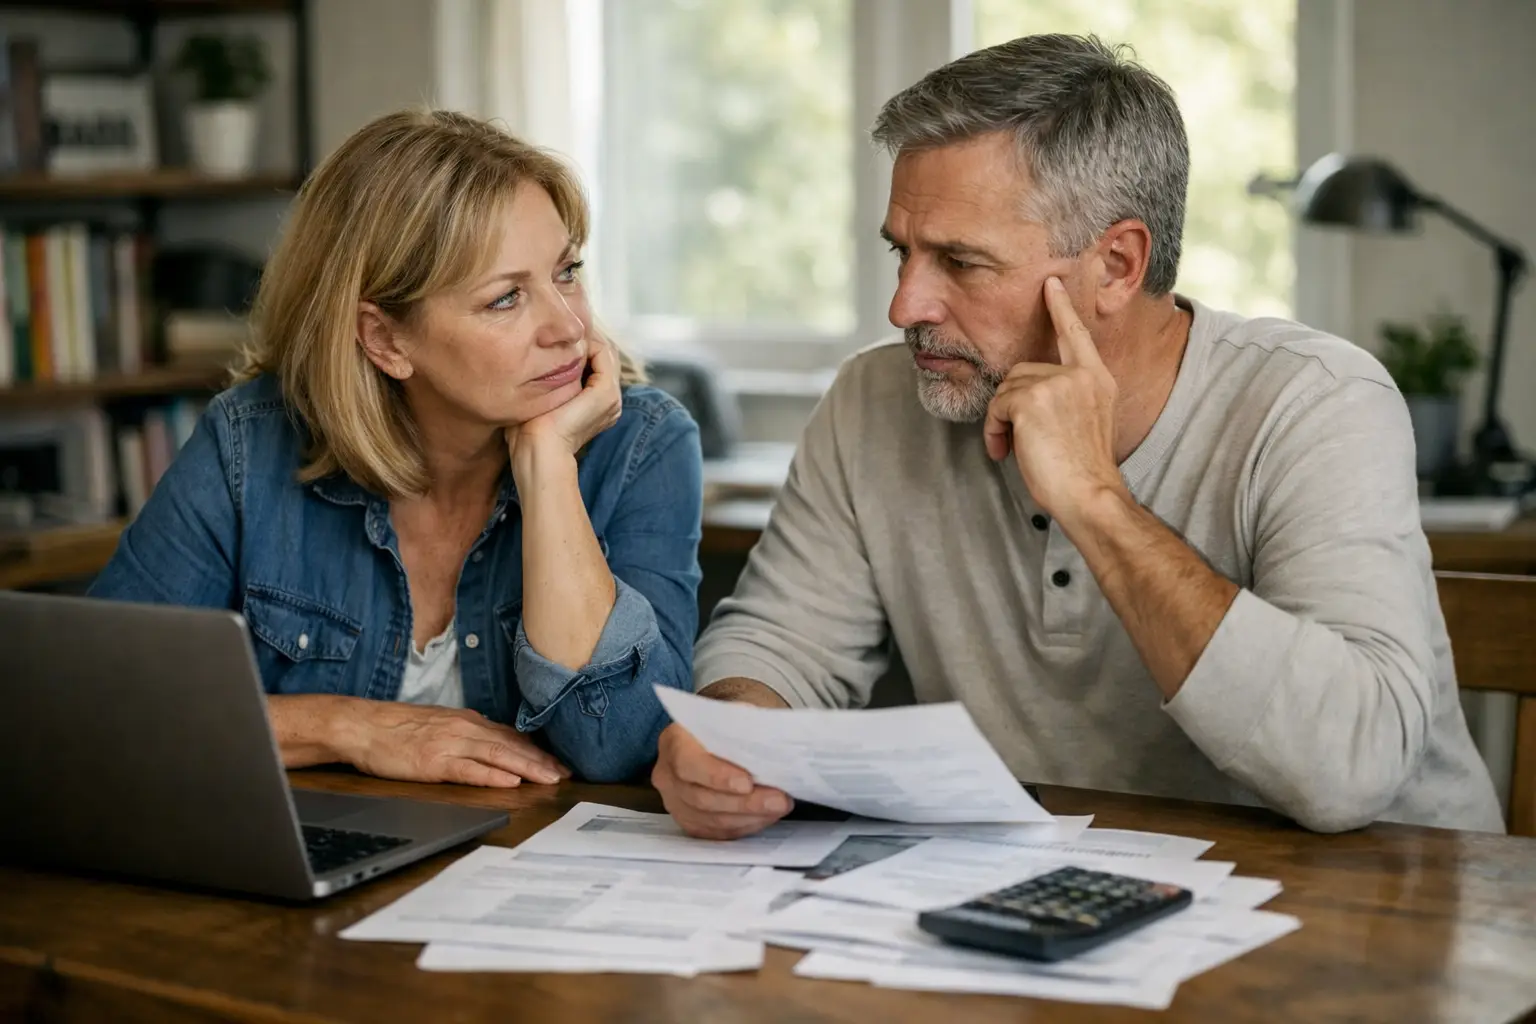
Retirement is a dilemma for a couple in their 60s who report $4 million in savings but diverge sharply on whether to stop working. The wife argues they cannot afford to retire; the husband cites fears about healthcare, long-term care, inflation, a prolonged bear market and the possibility of living to 95. A recent disagreement over an $8,000 trip to Italy has crystallized the tension between current lifestyle choices and future financial security.
Key variables shape this decision beyond the headline account balance. Longevity risk—outliving assets—matters most when planning for an extended retirement span. Market volatility creates sequence-of-returns risk that can reduce withdrawal sustainability early in retirement. Meanwhile, gaps in coverage, notably for long-term custodial care, can produce large, unpredictable expenses. Institutions such as Medicare do not typically cover extended nursing-home stays, and decisions about when to claim benefits from Social Security can also affect lifetime income, so timing and coverage details will influence the couple’s margin for error.
Rather than a single right answer, financial-planning frameworks can translate the couple’s situation into concrete scenarios. Common approaches include projecting cash flows under varying spending rates, stress-testing portfolios against market downturns, and estimating potential long-term care costs with and without insurance. Options that preserve flexibility include a phased retirement, part-time work, or keeping a defined plan for large discretionary expenses. Couples often find value in third-party analysis—such as a certified financial planner—to model outcomes and present trade-offs without emotion driving every decision.
At stake are both financial resilience and household harmony. The immediate consequence of unilateral vetoes on travel is domestic strain; the longer-term consequence of underestimating costs is reduced security in advanced age. A disciplined review of spending needs, insurance gaps, and realistic return assumptions can help determine whether continuing full-time work is necessary or whether a measured shift into retirement is affordable. Clear communication and scenario-based planning will reveal whether the couple’s resources align with their expectations for lifestyle and risk tolerance.