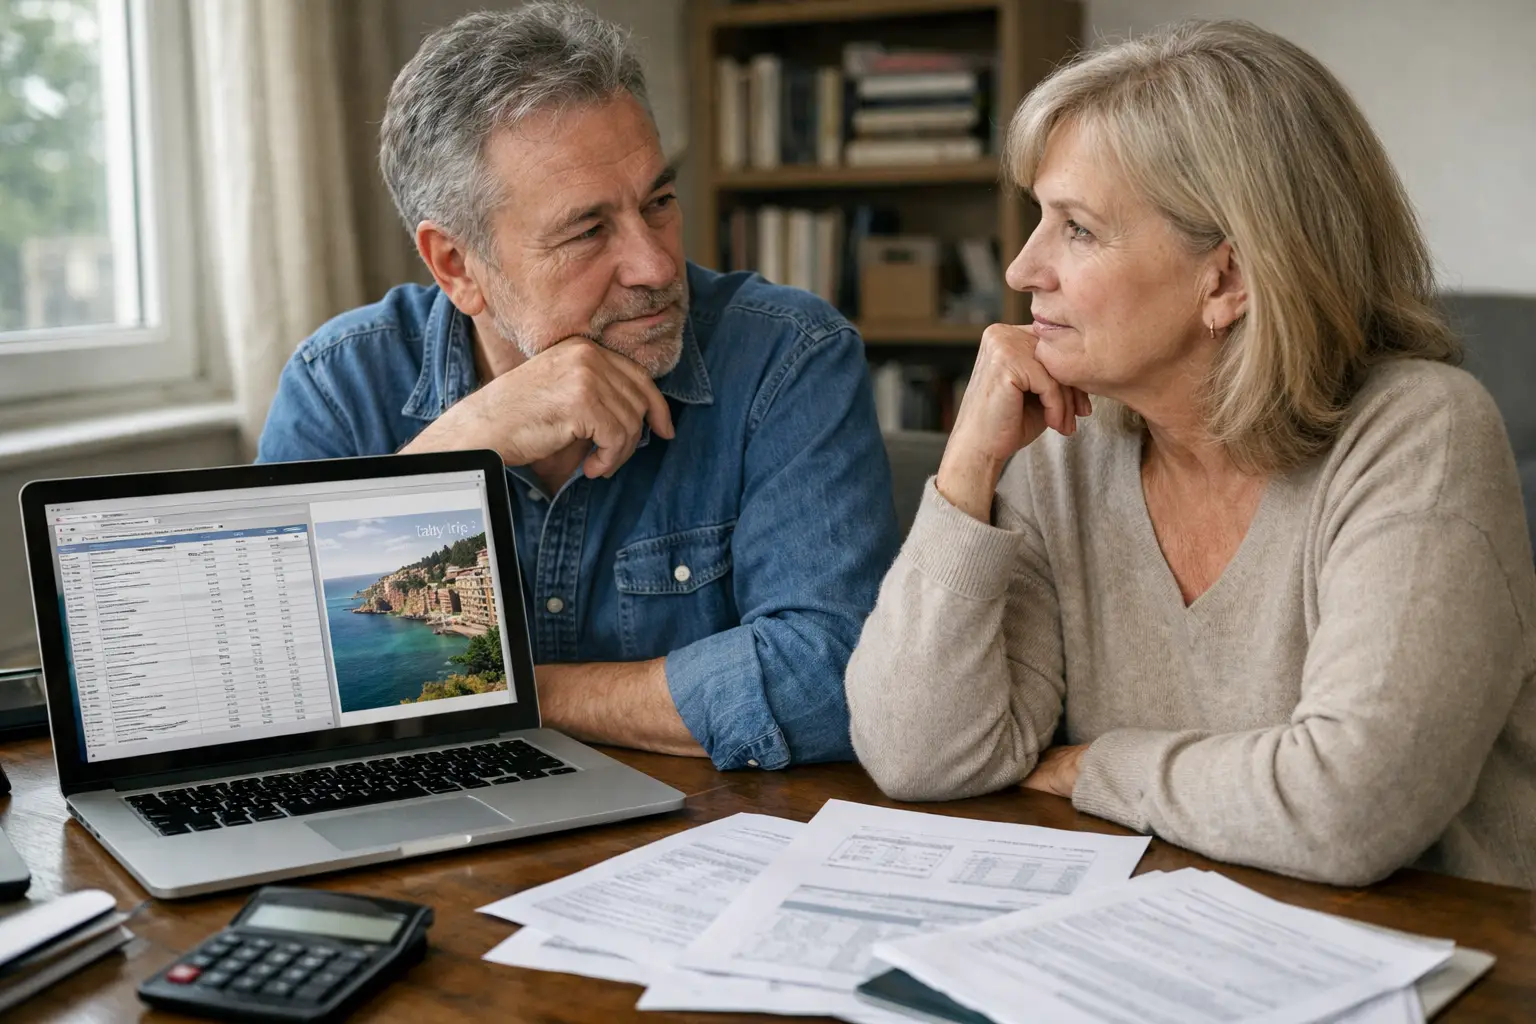
My wife and I are in our 60s, hold $4 million in savings and face a clear disagreement: she says they cannot afford to retire, and I recently vetoed her proposed $8,000 trip to Italy. The couple’s concerns include healthcare and long-term care costs, the effects of inflation, the prospect of an extended bear market and living into their mid-90s. Those worries are common and deserve a methodical assessment before deciding whether to continue working.
From a financial planning perspective, the headline number — $4 million — suggests substantial resources, but adequacy depends on spending, portfolio allocation and sequence-of-returns risk. Inflation and rising medical expenses can erode purchasing power over time, while prolonged market declines early in retirement can force heavier withdrawals. Estimating likely annual spending, isolating discretionary items such as international travel, and modeling different market and inflation scenarios are essential steps to understand how long assets may last under plausible conditions. Reliable planning also requires realistic estimates for potential long-term care needs.
Choosing to keep working, even part time, changes several levers: it can postpone withdrawals, reduce sequence risk, and extend the time for investments to recover after downturns. It may also preserve employer-sponsored benefits if applicable. Conversely, continuing to work has nonfinancial consequences — including the personal trade-offs between income and time for family, travel and health. The immediate conflict over the $8,000 trip highlights the need to reconcile financial caution with quality-of-life priorities and to reach a shared retirement vision.
Practical next steps include assembling a detailed budget, running retirement scenarios that incorporate medical and long-term care estimates, and considering phased retirement or targeted spending buffers. Discussing options together and involving a certified financial planner can clarify risks and probabilities without relying on intuition alone. Gathering cost information for healthcare and long-term care, and reviewing investment strategy and withdrawal pacing, will produce a fact-based roadmap to determine whether continuing to work is necessary or whether retirement can proceed with confidence.