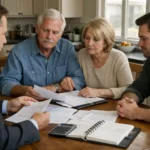
Giving money while alive can be more useful to adult children and grandchildren than leaving assets only through an inheritance. A contribution made at the right time may help with education, housing, debt reduction or childcare, while the giver is still able to see the impact. But family support is not simply a generous act; it is a financial decision that belongs within a broader personal finance plan.
The central rule is that retirement must come first. Before making gifts, retirees and near-retirees need a clear view of expected income, essential expenses, healthcare costs, housing needs and emergency reserves. Money transferred to family is usually no longer available for the giver’s future care, and that loss of flexibility can become serious if markets fall, medical needs rise or living arrangements change. A sustainable gift is one that does not compromise the donor’s ability to remain independent.
Tax and legal rules also matter. In the United States, gifts may involve reporting obligations and should be reviewed in light of estate plans and lifetime transfers. The Internal Revenue Service provides guidance on federal gift tax rules, but state and personal circumstances can change the outcome. Families with trusts, property transfers or cross-border issues should involve qualified tax and legal professionals before moving significant sums. Clear records are important, especially when several heirs are involved.
Family dynamics can be as important as financial rules. Parents and grandparents often want to treat relatives fairly, but equal gifts are not always perceived as equitable when needs differ. A gift for a home deposit, tuition or medical expense may create expectations among siblings or grandchildren. Written notes explaining whether money is a gift or a loan can reduce confusion. Transparency, when appropriate, may help prevent disputes later, particularly when lifetime giving affects an eventual estate planning strategy.
A practical approach is to set a gifting budget that is separate from essential retirement assets and to review it regularly. Smaller recurring gifts may be easier to manage than a large one-time transfer, while direct payment for a defined purpose can give both sides clarity. Professional advice from a fiduciary financial planner, estate attorney or tax adviser can help align generosity with long-term security. The goal is not to discourage giving, but to make sure support for the next generation does not create financial vulnerability for the one providing it.