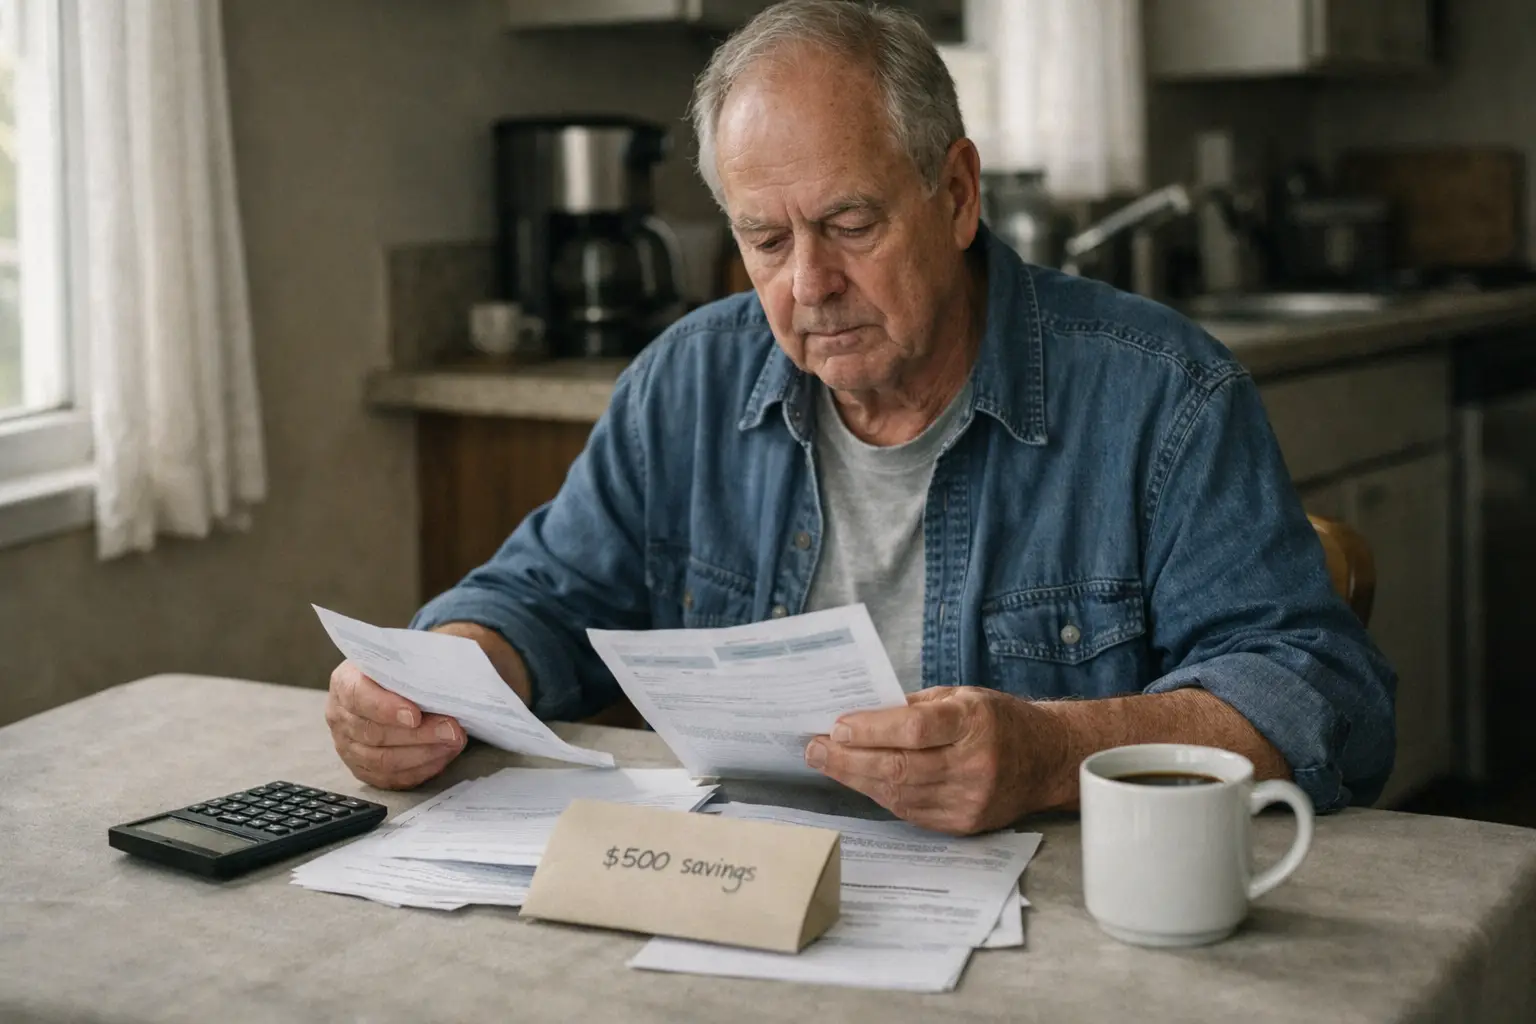
A retirement without reserves leaves little room for error. The case of a 66-year-old American living mainly on Social Security and holding just $500 in savings illustrates a financial reality far removed from conventional retirement planning. With no meaningful cash buffer, even a modest medical bill, car repair or rent increase can become a crisis rather than a manageable expense.
The central issue is not investment strategy but financial survival. Social Security provides a foundation for millions of older Americans, but the Social Security Administration presents it as retirement income designed to replace only part of prior earnings. For retirees who have little or no pension, no substantial savings and limited ability to work, the monthly benefit often becomes the entire household budget. That makes every fixed cost, from housing to utilities, more consequential.
For someone in this position, the most immediate step is usually a full review of available public and local assistance, not a search for high returns. Programs connected to food, health coverage, energy bills and housing may reduce pressure on a monthly budget. Eligibility varies by state and personal circumstances, but official tools such as Benefits.gov can help identify benefits that may be available. Local aging offices and community nonprofit services can also help older residents navigate applications and documentation.
Debt and recurring expenses may require the same level of scrutiny. A retiree with only a small emergency fund cannot safely absorb high-interest balances, unnecessary subscriptions or avoidable fees. Housing is often the largest constraint: when rent or property costs consume most income, other choices shrink quickly. In some cases, older adults explore shared housing, relocation, senior housing lists or payment plans with service providers. These are practical options, but each depends on personal health, family ties, transportation and the local cost of living.
The broader significance is clear: retirement security is uneven, and age alone does not guarantee stability. The question posed by a 66-year-old with almost no savings is not an isolated budget puzzle; it reflects the vulnerability of retirees who reach later life without a financial cushion. For them, hope often depends less on market performance than on benefit access, expense control, reliable advice and the ability to prevent one unexpected bill from triggering a deeper crisis.