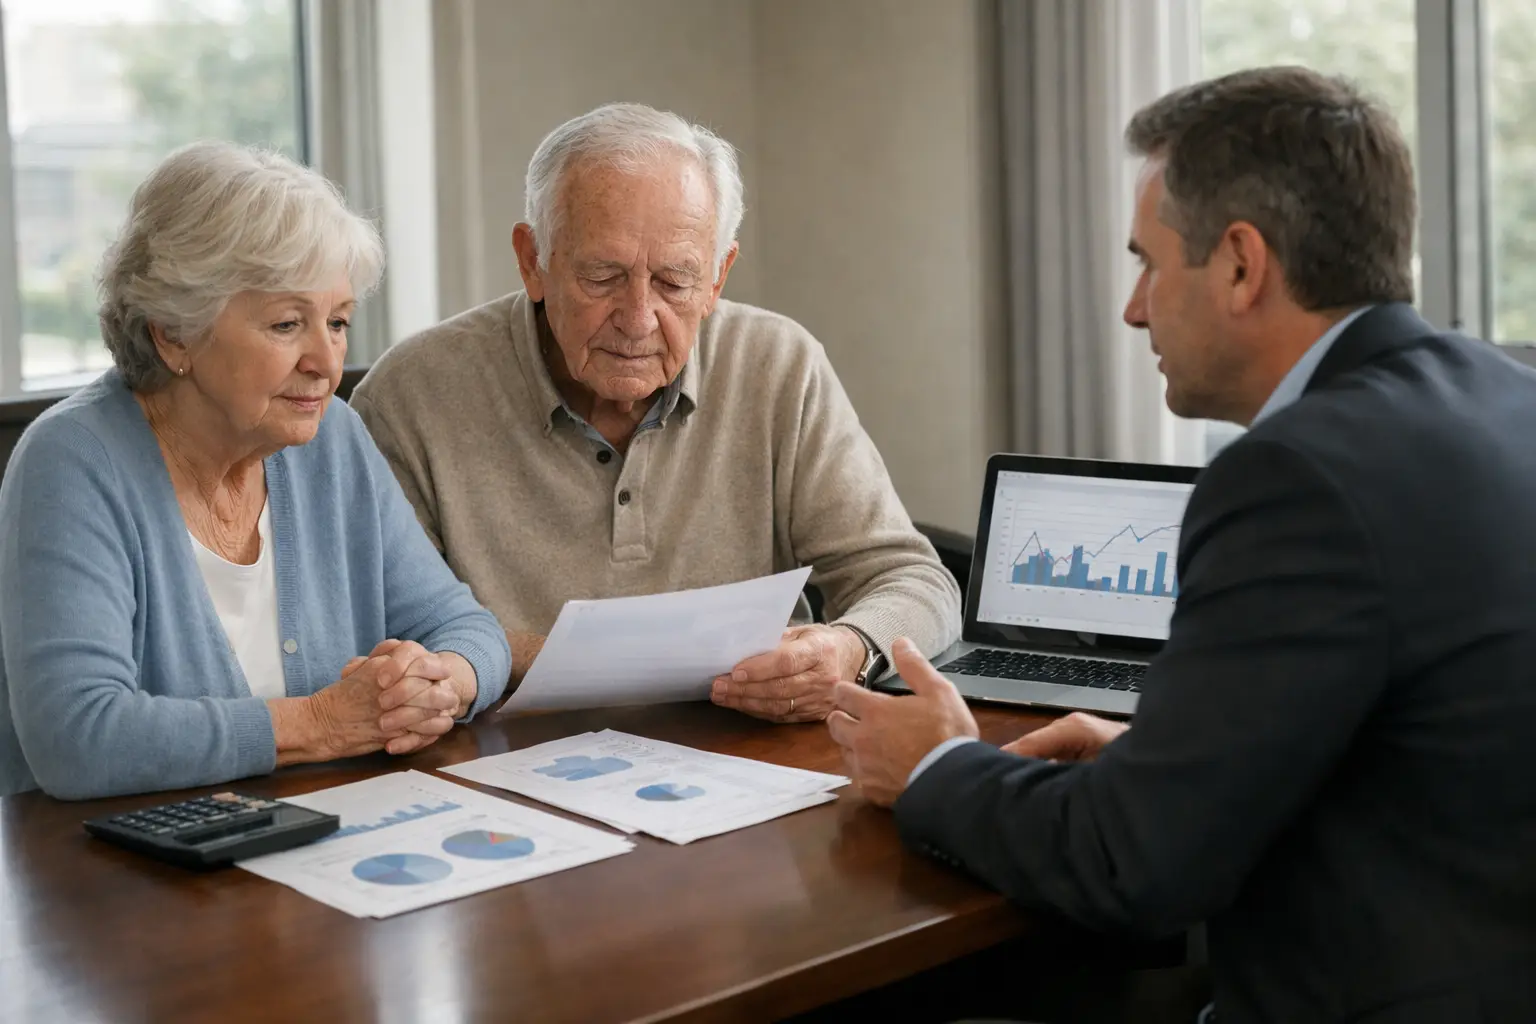
A retirement tax question can look counterintuitive when day-to-day finances are already secure. A couple in their 80s, with $950,000 held in traditional IRAs, says their essential living costs are covered by $110,000 a year from pensions and Social Security. Yet their financial adviser is encouraging Roth conversions, prompting an understandable concern: why move taxable retirement money now?
The issue sits at the intersection of retirement planning, income taxes and estate strategy. Money in a traditional IRA has generally not yet been taxed, and withdrawals are usually treated as ordinary income. A Roth conversion moves assets into a Roth IRA, creating taxable income in the year of conversion, while future qualified Roth withdrawals can be tax-free under rules set by the Internal Revenue Service. For retirees whose pensions and Social Security already cover bills, the argument is not usually about funding current spending. It is often about managing the tax character of assets that may otherwise remain in traditional accounts.
Age does not automatically make a conversion irrelevant. People in their 80s with traditional IRAs are subject to required minimum distributions, which can increase taxable income even when the cash is not needed for living expenses. Converting part of an IRA can reduce the balance that drives future required withdrawals, but it also accelerates tax into the current year. That trade-off is central. A conversion that appears efficient at one tax rate can be less attractive if it pushes the household into a higher bracket or affects other income-linked costs. The calculation is especially sensitive for retirees who already have stable taxable income from pensions.
The other reason advisers raise Roth conversions late in retirement concerns heirs. Traditional IRAs left to beneficiaries can carry future tax obligations, while inherited Roth assets may offer different planning outcomes if the rules are met. That does not mean a conversion is automatically beneficial. It depends on the owners’ taxable income, charitable intentions, state taxes, expected longevity, estate goals and the tax position of beneficiaries. In some households, paying tax now may simplify later planning; in others, the upfront cost may outweigh the benefit.
For a couple with nearly $1 million in traditional IRAs and guaranteed income covering expenses, the recommendation is not inherently bizarre, but it requires a clear written explanation. The relevant question is not whether Roth conversions are fashionable, but what specific problem they are meant to solve: lower lifetime taxes, smaller required distributions, more flexible inheritance planning or some combination of those goals. A prudent review would compare conversion amounts across several years, estimate the tax bill, and show what happens if no conversion is made.