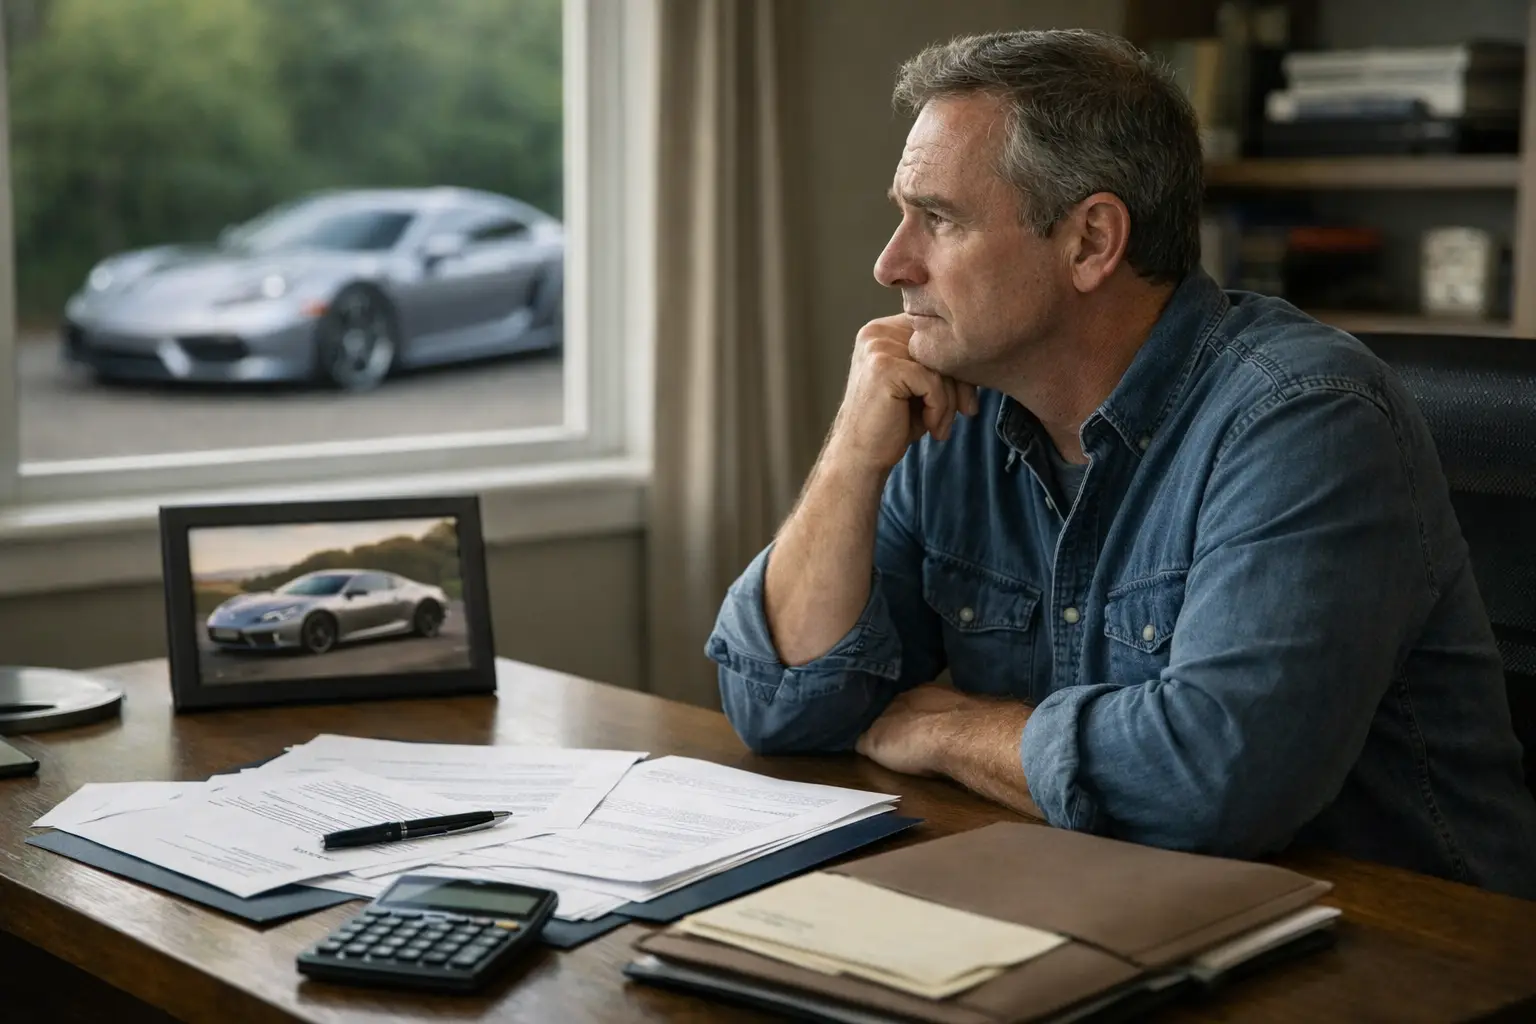
A $210,000 sports car has become the symbol of a larger financial decision for a 55-year-old married man living with a brain tumor. He is considering buying a Porsche, while also wanting to protect his family’s long-term security and leave a meaningful inheritance for his two sons. The situation brings together two pressures that often collide in serious illness: the desire to enjoy wealth while there is still time, and the responsibility to make sure dependents are not left exposed.
The facts of the case are limited but significant. The buyer is married, has two children and is facing an uncertain medical future. A purchase of this size is not only a question of affordability at the checkout; it can affect liquidity, retirement projections, insurance needs, tax planning and the eventual distribution of assets. In personal finance, a high-value discretionary purchase late in a household’s earning life can have very different consequences depending on whether the family already has adequate savings, low debt and a clear estate plan.
For households dealing with a serious diagnosis, the first priority is often clarity. That includes confirming who owns which assets, how accounts are titled, whether beneficiary forms are current and whether a will, trust or health-care directive reflects present wishes. Official tax rules can also influence how estates are handled, particularly when investments, retirement accounts or appreciated assets are involved; guidance from the Internal Revenue Service can help frame those obligations, while legal and financial professionals can adapt them to a specific family situation. None of these steps decides whether the car should be bought, but they establish the real cost of the decision.
The emotional dimension is equally important. A diagnosis that may shorten life can change the meaning of money, shifting attention from accumulation to experience, autonomy and dignity. At the same time, a promised legacy is not measured only by the size of an inheritance. It may also depend on whether surviving relatives are spared confusion, forced asset sales or disputes over intentions. In that sense, the question is not simply whether a luxury car is justified, but whether the purchase fits inside a broader plan that the spouse understands and the family can sustain.
A careful decision would require comparing the Porsche’s full cost with the household’s available assets, expected medical expenses, income needs for the surviving spouse and intended gifts to the two sons. If those goals remain secure after the purchase, the car may represent a chosen use of personal wealth. If they are weakened, the same purchase could undermine the legacy the man wants to preserve. The dilemma shows why end-of-life financial planning is rarely about numbers alone: it is about aligning money with time, family obligations and the life a person still wants to live.