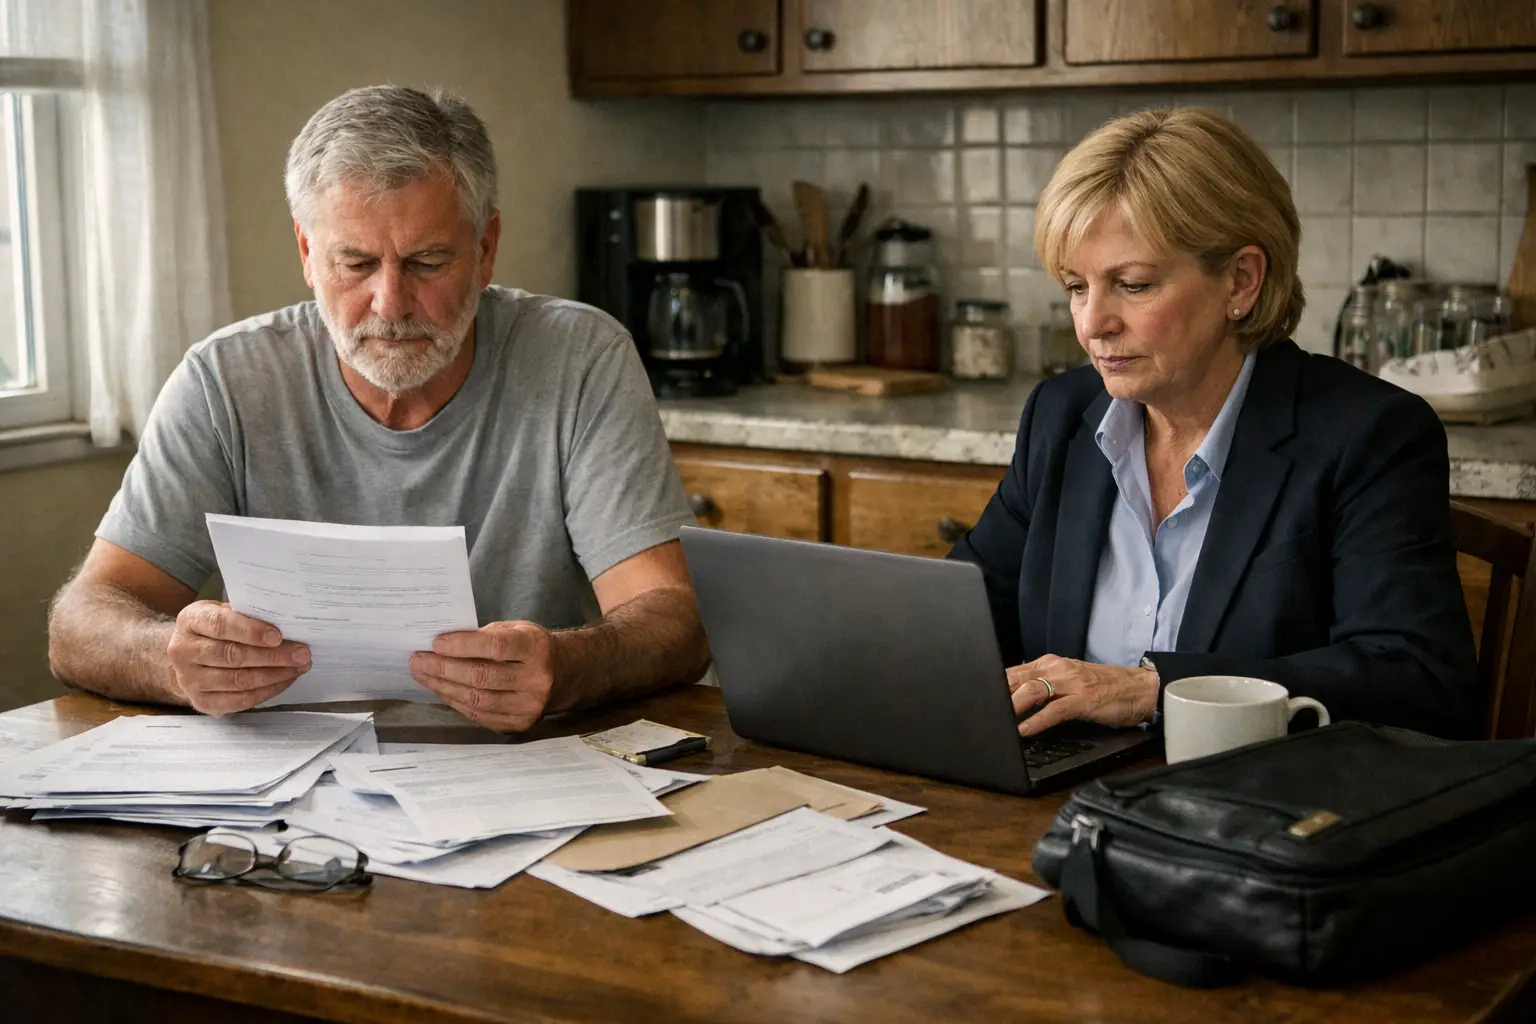
A familiar retirement dilemma is emerging inside many households: one partner has left the workforce and settled into life after work, while the other continues to face early alarms, long commutes and growing fatigue. In this case, the retired spouse is 64 and content with his decision, while his wife says she is exhausted by a 6 a.m. start and a 50-minute journey to work. The disagreement is not only about employment. It is about fairness, timing and how couples share the costs and benefits of retirement.
The central issue is not whether a 64-year-old retiree is entitled to stop working. Retirement often depends on health, savings, job conditions and benefit rules. The more difficult question is whether one spouse can reasonably expect the other to keep working without a shared plan. In couples’ finances, income is rarely just an individual matter. A salary may support household spending, insurance coverage, debt payments or future security. But paid work also carries personal costs, especially when a worker is physically or emotionally drained by the routine required to maintain that income.
Retirement planning becomes strained when the decision is made unevenly. If one partner leaves work and the other feels left behind, resentment can build quickly, even in financially stable households. A 50-minute commute is not a minor detail; it affects sleep, health, time at home and the ability to sustain employment. The fact that one spouse is happily retired may sharpen the contrast, particularly if the working partner feels her exhaustion is being treated as secondary to the household budget. A durable plan usually requires both partners to see the full balance sheet: money coming in, expenses going out, health needs, retirement accounts and the nonfinancial burden of continuing to work.
For households nearing retirement, the practical step is to replace assumptions with a written comparison of options. That can include what happens if the working spouse reduces hours, changes jobs, works remotely, sets a retirement date or stops sooner than expected. Where public benefits are involved, couples should verify eligibility and timing through official sources such as the Social Security Administration, rather than relying on estimates or habit. Such a review does not decide the emotional question, but it can clarify whether continued work is necessary, temporary or simply preferred by one partner.
The fairness question is therefore less about one spouse’s retirement status than about mutual consent. A partner who is already retired can reasonably worry about long-term finances; a partner still working can reasonably object to carrying the burden alone. The outcome most likely to preserve both financial stability and the relationship is a transparent plan with dates, trade-offs and limits. Without that, retirement stops being a shared milestone and becomes a source of unequal pressure inside the marriage.